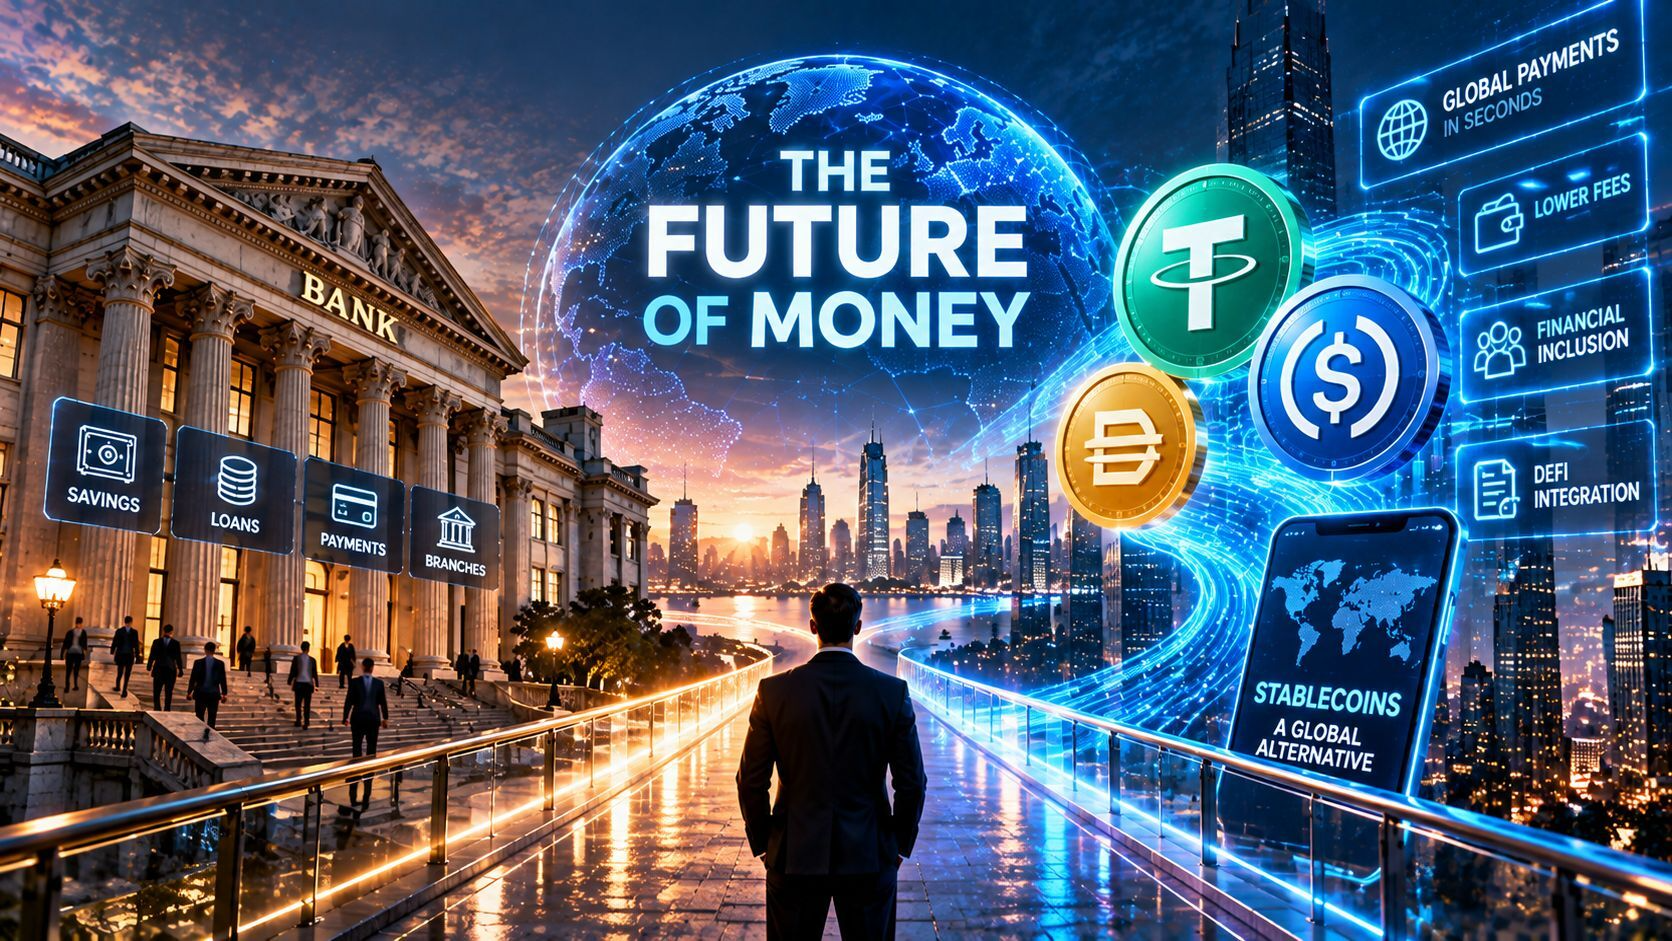
Stablecoins could reshape payments and compete with banks without replacing their broader financial services.
Research highlights potential effects on bank deposits, lending, liquidity, and demand for US Treasury securities.
By 2030, banks and stablecoin issuers may increasingly integrate blockchain technology and traditional financial infrastructure.
The global banking system is facing an unusual challenge. For centuries, banks have played a central role in storing money, processing payments, and providing credit.
Today, a new generation of digital financial instruments is beginning to challenge parts of that model.
Stablecoins, which are designed to maintain a relatively constant value against traditional currencies, allow people and businesses to transfer money through blockchain networks.
Their development raises an important question: could the financial system eventually operate without the traditional bank accounts and payment infrastructure that most people use today?
For investors and readers following the transformation of global finance, understanding the difference between digital money and conventional banking is becoming increasingly important.
Financial news platforms such as the Coinspot site help audiences follow developments in digital assets, payment technology, and the changing financial landscape.
Yet the most consequential aspect of stablecoin adoption may not be the technology itself.
It may be the possibility that money could move through new networks while banks gradually lose their exclusive position as the primary gateway to financial services.
The banking monopoly that was never quite a monopoly
Banks have traditionally performed several important economic functions.
They provide accounts where households and businesses can hold money.
They process payments, manage financial records, and extend credit to borrowers.
These activities are closely connected, but they are not identical.
A customer may use a bank account primarily to receive wages and pay bills. Another customer may depend on the same institution for a mortgage or business loan.
Stablecoins challenge the payment and money-holding components of this arrangement.
They do not automatically replace the credit creation, financial analysis, and regulatory responsibilities performed by banks.
This distinction is essential.
A technology that makes money transfers faster does not necessarily create a complete alternative banking system.
The future may involve greater competition in selected services rather than the disappearance of traditional financial institutions.
What makes a stablecoin different from money in a bank account?
A dollar-backed stablecoin is generally designed to maintain a value close to one US dollar.
Its issuer may hold reserves intended to support redemption, depending on the product’s structure and applicable regulations.
A bank deposit represents a claim against a regulated financial institution.
These arrangements may appear similar from the customer’s perspective, but their legal and economic foundations are different.
Bank deposits can be protected by deposit insurance within applicable limits and jurisdictions.
Stablecoins do not automatically provide equivalent protection.
Banks also participate in payment and settlement systems supported by central banks.
Stablecoin transfers can occur on blockchain networks, where the reliability of settlement depends on the underlying technology and financial arrangements.
Stablecoins vs. traditional bank deposits
| Feature | Traditional Bank Deposit | Reserve-Backed Stablecoin |
|---|---|---|
| Primary Issuer | Regulated commercial bank | Stablecoin issuer |
| Value | Denominated in conventional currency | Designed to track a reference currency |
| Deposit Insurance | May apply within legal limits | Generally not equivalent to insured deposits |
| Transfer Infrastructure | Banking and payment networks | Supported blockchain networks |
| Operating Hours | Depends on payment system | Blockchain transfers can operate continuously |
| Credit Creation | Banks can lend against their funding base | Stablecoin issuance does not inherently create loans |
| Redemption | Withdrawal or transfer through banking services | Depends on issuer rules and available intermediaries |
| Main Risks | Bank failure, account restrictions, fraud | Reserve, issuer, redemption, custody, and technical risks |
The comparison reveals why stablecoins may compete with bank accounts without providing all the same financial protections.
The $300 billion experiment in digital money
Stablecoins have expanded significantly over recent years.
According to the International Monetary Fund, their combined market capitalization stood at approximately $300 billion in August 2026.
This represents meaningful growth, but it remains relatively small compared with the conventional banking system.
The Bank for International Settlements reported that the global stablecoin market was worth approximately $315 billion in early April 2026.
For comparison, U.S. bank deposits alone amounted to roughly $8 trillion in the BIS comparison.
The difference in scale is substantial.
However, financial innovation does not always begin by replacing an entire established market.
New technologies often gain adoption in specialized activities before expanding into broader commercial use.
Stablecoins have already become important instruments for transactions within digital asset markets.
The next question is whether their role in ordinary economic payments will grow sufficiently to challenge traditional financial institutions.
The payments battle could be decided before the banking battle
Payments are the most immediate area of competition.
Traditional financial institutions operate through complex networks that connect banks, payment processors, clearing systems, and currency conversion providers.
These arrangements support enormous transaction volumes.
However, international payments can still involve delays and substantial fees.
Stablecoins provide an alternative method of transferring value.
A transaction can be recorded on a blockchain without passing through every intermediary involved in a conventional cross-border bank transfer.
This may reduce friction in certain payment arrangements.
Yet the benefits depend on the complete process.
Users often need to convert conventional money into stablecoins before sending funds.
Recipients may then need to convert those tokens into local currency.
The conversion process can introduce fees, delays, and additional financial risks.
The future of payments will not be decided by which system moves digital tokens fastest.
It will be decided by which system delivers money reliably, affordably, and safely to the people who need it.
The most successful payment solutions may combine blockchain settlement with familiar financial services.
Why stablecoin transaction volumes can be misleading
Stablecoin transaction statistics frequently attract attention because they involve enormous numbers.
Some estimates suggest that total stablecoin transfers exceeded $30 trillion during 2025.
However, not every blockchain transfer represents an economic payment.
Funds may move between trading platforms, institutional accounts, and automated financial applications.
Some transactions involve internal treasury management or speculative trading.
The BIS estimated that payment-related stablecoin flows amounted to approximately $390 billion in 2025.
This is considerably smaller than the headline figure for total transfers.
The distinction matters when evaluating the possibility of stablecoins replacing banking services.
A technology can process substantial financial activity without becoming a widely used payment method for households and businesses.
The numbers behind stablecoin adoption
| Metric | Approximate Figure | What It Indicates |
|---|---|---|
| Stablecoin Market Capitalization, August 2026 | $300 billion | Outstanding stablecoin value |
| Total Stablecoin Transfers, 2025 | Over $30 trillion | Broad blockchain transaction activity |
| Payment-Related Stablecoin Flows, 2025 | $390 billion | Estimated payments rather than all transfers |
| Dollar Share of Stablecoin Market | Nearly 99% | Dominance of dollar-denominated products |
| U.S. Bank Deposits in BIS Comparison | Around $8 trillion | Scale of conventional banking |
The figures show both the sector’s progress and the distance it must travel before becoming a mainstream alternative to banking.
The deposit problem banks are beginning to study
Banks rely on deposits as an important source of funding.
Customer balances help support lending and other financial activities.
If substantial amounts of money move from bank deposits into stablecoins, the composition of bank funding could change.
A customer holding digital dollars outside a conventional bank account may no longer provide the same funding to that institution.
At the same time, stablecoin issuers often maintain reserve assets through banks and government securities markets.
Some money may therefore return to the banking system in a different form.
However, the economic effects are not necessarily neutral.
Research published by the Federal Reserve Bank of New York in 2026 examined how stablecoin activity can influence banking liquidity and lending.
The researchers found evidence that banks exposed to stablecoin-related deposits face additional liquidity demands.
Their analysis also indicated that these banks may hold more reserves and maintain smaller loan portfolios relative to comparable institutions.
This suggests that stablecoin growth could influence the banking system even without directly replacing it.
Could stablecoins make mortgages more expensive?
The connection between stablecoins and mortgages may seem indirect.
However, bank funding conditions influence the availability and cost of credit.
If stablecoins attract substantial deposits away from banks, some financial institutions may need to obtain funding from more expensive sources.
Higher funding costs can affect lending decisions.
Banks may respond by increasing loan rates, reducing credit availability, or changing their balance sheet strategies.
The European Central Bank has examined the potential effects of stablecoin adoption on monetary policy transmission and bank lending.
Its research suggests that large-scale substitution of bank deposits could weaken lending to businesses in economies where banks remain the dominant source of credit.
However, these effects depend on the scale of adoption and the structure of the financial system.
Countries with developed capital markets may be able to absorb some changes more easily.
The important point is that replacing bank deposits with stablecoins could have consequences beyond payment convenience.
It may also change how credit reaches households and businesses.
The treasury market connection nobody expected
Major dollar-backed stablecoin issuers often hold substantial reserves in short-term US government securities and other liquid financial instruments.
These assets are intended to support the value and redemption of outstanding tokens.
As stablecoin circulation increases, demand for reserve assets may also grow.
This creates a connection between blockchain-based money and government debt markets.
The IMF has highlighted the increasing importance of stablecoin issuers as investors in US Treasury bills.
In principle, additional demand for short-term government securities could influence borrowing costs.
However, the relationship also creates financial stability concerns.
If large numbers of stablecoin holders request redemption simultaneously, issuers may need to sell reserve assets.
Under stressed conditions, those sales could affect market liquidity.
Stablecoins therefore do not operate entirely outside conventional finance.
Their financial foundations often depend on the same government securities and banking relationships that support traditional monetary systems.
What happens when everyone wants their dollars back?
A stablecoin is designed to maintain a stable value, but that stability depends on confidence.
Users must believe that the issuer can meet redemption obligations.
They must also trust the quality and accessibility of reserve assets.
If confidence weakens, holders may attempt to redeem or sell their tokens.
A large wave of selling can cause the market price to move below its intended value.
The IMF’s 2026 research on stablecoin stability emphasized the importance of reserve quality and appropriate financial safeguards.
The problem resembles certain forms of liquidity stress experienced by conventional financial institutions.
Even assets that are considered relatively safe can become difficult or expensive to liquidate during market disruptions.
The four layers of stablecoin risk
- Reserve risk: The backing assets may lose value or become difficult to sell.
- Redemption risk: Users may face delays, restrictions, or limited direct access to the issuer.
- Operational risk: Custodians, payment providers, or technical systems may experience failures.
- Market confidence risk: A loss of trust may cause the token’s trading price to deviate from its target.
These risks are especially important for users who treat stablecoins as equivalent to insured bank deposits.
They are not necessarily interchangeable.
The Hidden Advantage Banks Still Possess
Stablecoins can provide efficient transfers, but banks offer a broader range of financial services.
They assess borrowers, provide credit, manage customer relationships, and operate within established legal frameworks.
They also provide services that consumers may take for granted.
A customer can dispute certain unauthorized transactions.
Businesses can obtain financing based on cash flow and financial history.
Households can access mortgages, savings products, and other regulated services.
Stablecoin networks do not automatically reproduce these functions.
Blockchain transactions can also be difficult to reverse.
This creates challenges when users send funds to incorrect addresses or become victims of fraud.
Services that stablecoins cannot automatically replace
- Credit underwriting: Evaluating whether individuals and businesses can repay loans.
- Deposit protection: Providing legally established safeguards for eligible customer balances.
- Consumer dispute resolution: Investigating and resolving certain payment problems.
- Financial advice: Supporting savings, investment, and retirement planning decisions.
- Business financing: Providing working capital and longer-term credit facilities.
- Regulatory compliance: Monitoring transactions and meeting legal obligations.
- Emergency liquidity: Accessing established financial support arrangements under applicable rules.
Stablecoins may improve certain services, but replacing the complete banking model would require much more than faster payments.
The Rise of Banks That Use Blockchain Instead of Fighting It
Traditional banks are increasingly exploring tokenized forms of money.
Tokenized deposits represent bank liabilities recorded through blockchain-based or related distributed ledger infrastructure.
They can provide some of the technological features associated with stablecoins while remaining connected to regulated banking relationships.
This creates an alternative path for financial innovation.
Rather than losing customers to independent stablecoin issuers, banks may develop digital settlement systems of their own.
The IMF’s May 2026 analysis of tokenized finance highlighted the potential for tokenized deposits to support payments, settlement, and liquidity management.
Such systems may allow financial institutions to automate selected transactions and maintain synchronized financial records.
However, tokenized deposits also introduce new operational requirements.
Continuous settlement may increase the need for real-time liquidity management.
Financial institutions must also manage cybersecurity, governance, and system reliability.
The result could be a banking industry that adopts blockchain technology rather than being displaced by it.
The regulatory contest between the United States and Europe
Stablecoin regulation is becoming a major factor in the future of digital money.
The United States and European Union have developed different approaches.
The US GENIUS Act focuses on payment stablecoins, including requirements involving issuance, reserve backing, and supervision.
The European Union’s Markets in Crypto-Assets Regulation establishes a broader framework covering several categories of digital assets and related service providers.
A July 2026 European Parliament briefing compared these approaches and highlighted differences in how they connect stablecoin activities with existing financial law.
The regulatory direction matters because financial institutions need clarity before adopting new payment systems.
Rules can influence which companies are allowed to issue stablecoins, what assets can support them, and how customers can redeem their holdings.
How regulation could shape the market
| Regulatory Issue | Why It Matters |
|---|---|
| Reserve Requirements | Influences the quality of assets supporting stablecoins |
| Redemption Rights | Determines how holders can exchange tokens for conventional money |
| Issuer Supervision | Establishes accountability and oversight |
| Customer Identification | Supports compliance with financial crime rules |
| Operational Resilience | Addresses technical failures and service disruptions |
| Cross-Border Coordination | Helps manage international transactions |
| Consumer Protection | Clarifies rights and remedies for users |
Clearer rules could encourage adoption.
However, regulatory compliance may also increase operating costs and limit certain business models.
The digital dollar could become more global than the physical dollar
Dollar-denominated stablecoins dominate the current market.
This reflects the US dollar’s established role in international trade, finance, and savings.
Digital dollar tokens may make dollar exposure more accessible to people outside the United States.
In some countries, residents face restrictions or high costs when opening conventional dollar accounts.
Stablecoins can offer another method of holding dollar-denominated value.
This may be attractive in economies experiencing high inflation or currency instability.
However, widespread adoption could weaken demand for local currencies.
The Bank for International Settlements warned in 2026 that stablecoins could accelerate digital dollarization in emerging economies.
If businesses and households increasingly use dollar-backed tokens for savings and payments, domestic monetary authorities may face additional challenges.
This creates a difficult policy balance.
Stablecoins may improve access to financial services while reducing the effectiveness of national monetary policy.
Can stablecoins reduce the cost of sending money abroad?
International remittances are one of the most frequently discussed applications.
Workers sending money to relatives abroad may encounter substantial fees and exchange rate spreads.
Traditional remittance providers operate through networks of banks, agents, and local payment systems.
Stablecoins could simplify selected stages of this process.
A sender may purchase digital dollars and transfer them through a blockchain network.
The recipient can then convert the tokens into local currency.
However, the complete transaction may still involve conversion fees and financial intermediaries.
The IMF reported in August 2026 that the average global remittance cost was approximately 6.5%.
It also noted that the cost of sending $200 through stablecoin-based arrangements can vary substantially between payment corridors.
This means stablecoins may offer savings in some circumstances without being universally cheaper.
What determines the real cost of a stablecoin payment?
- The cost of purchasing stablecoins.
- Blockchain transaction fees.
- Wallet or payment provider charges.
- Currency conversion spreads.
- Local withdrawal fees.
- Compliance and identity verification requirements.
- The availability of reliable financial services in the recipient’s country.
The total cost matters more than the fee displayed by the blockchain network.
Why businesses may adopt stablecoins before consumers
Businesses engaged in international trade have practical reasons to improve settlement efficiency.
Cross-border payments can involve delays, currency conversion, and administrative costs.
A company may need to transfer money between subsidiaries or pay suppliers operating in different countries.
Stablecoins could support continuous settlement between compatible financial platforms.
This may improve certain treasury operations.
However, corporate adoption requires dependable accounting, compliance, and liquidity management.
Businesses must also understand the legal treatment of digital assets in relevant jurisdictions.
A financial system that provides rapid transfers but introduces uncertainty about ownership or redemption may not be attractive.
For this reason, enterprise adoption may favor regulated providers and integrated financial services.
The most successful solutions could operate largely behind the scenes.
Customers might use familiar payment interfaces while blockchain networks handle selected settlement functions.
The competition for the financial app of the future
The next generation of financial applications may combine traditional banking services with digital payment infrastructure.
A customer could potentially hold conventional deposits, access investment products, and transfer stablecoins through one interface.
Financial technology companies may compete with banks by offering more flexible international services.
Banks may respond by integrating similar capabilities into their own platforms.
Payment companies could also develop hybrid systems that connect conventional accounts with blockchain settlement networks.
This competition may improve financial services even if stablecoins never replace traditional banking.
Lower fees, better international transfers, and more convenient account management could become competitive priorities.
The ultimate winners may be companies that simplify the user experience rather than those that promote the most complex technology.
Three futures for Money by 2030
The future relationship between stablecoins and banks remains uncertain.
Several plausible outcomes deserve consideration.
Scenario one: stablecoins remain specialized payment instruments
Stablecoins continue serving digital asset markets and selected international payment activities.
Traditional banks retain their dominant role in deposits, lending, and everyday financial services.
Adoption grows, but stablecoins remain relatively small compared with the broader monetary system.
Scenario two: banks and stablecoins become integrated
Banks, payment companies, and stablecoin issuers develop connected financial infrastructure.
Customers gain access to faster international transfers while maintaining relationships with regulated institutions.
Tokenized deposits and stablecoins coexist.
This scenario could produce substantial innovation without replacing traditional banking.
Scenario three: digital money reshapes bank funding
Stablecoin adoption becomes large enough to influence household deposits and business treasury balances.
Banks face greater competition for funding.
Some lending activities migrate toward alternative financial institutions.
Regulators respond with new safeguards intended to preserve financial stability.
This outcome could transform banking economics, but it would also introduce significant policy challenges.
The financial institutions most exposed to disruption
Not every banking activity faces the same level of competition.
Payment services may be more directly affected than relationship-based lending.
Banks that depend heavily on international transfer fees could encounter competitive pressure.
Financial institutions with strong lending businesses and established customer relationships may be better positioned to adapt.
Payment companies may also experience changes in their business models.
A March 2026 IMF working paper examined stock market reactions to U.S. legislation supporting stablecoin payments.
The researchers estimated a negative valuation effect on established payment companies, with particularly strong reactions among businesses focused on cross-border payments.
This suggests that investors see stablecoins as a potentially meaningful competitive force.
However, market reactions are not proof that the expected disruption will occur.
Established companies may adapt by developing new services or integrating blockchain-based settlement.
The consumer protection test that could decide everything
Technology adoption depends heavily on trust.
Consumers need confidence that their money will remain accessible and that financial service providers will respond appropriately when problems occur.
Traditional banking systems have developed legal and operational protections over many decades.
Stablecoin services must address similar expectations.
Users may lose access to digital assets through compromised credentials, fraudulent transactions, or service provider failures.
A technically successful blockchain transfer does not guarantee that the intended recipient receives usable funds.
The quality of customer support, dispute handling, and financial safeguards will therefore influence mainstream adoption.
People do not adopt a payment system because its technology is impressive. They adopt it because it makes everyday financial activity easier without creating unacceptable risks.
The most important competition may be over consumer confidence rather than transaction speed.
The questions every stablecoin user should ask
Before treating a stablecoin as a substitute for money held in a bank account, users should understand the product’s financial structure.
A Practical Evaluation Checklist
- Who issues the stablecoin? Identify the legal entity responsible for the token.
- What assets support its value? Review the reserve structure and available disclosures.
- Who can redeem directly? Some issuers restrict direct redemption to approved participants.
- What happens during market stress? Consider whether redemption could become delayed or restricted.
- Which financial protections apply? Do not assume deposit insurance is available.
- How are assets stored? Understand custody arrangements and wallet security.
- What are the complete transaction costs? Include conversion and withdrawal expenses.
- Which laws apply? Regulatory protections and restrictions vary by jurisdiction.
These questions are particularly important when stablecoins are used for savings or substantial business transactions.
Why the end of banking is probably the wrong prediction
The idea that stablecoins will replace banks entirely overlooks the broader role of financial institutions.
Banks do much more than move money.
They provide credit, manage financial risks, support businesses, and operate within monetary systems backed by central banks.
Stablecoins can challenge certain payment and deposit functions.
However, they do not automatically reproduce the institutional arrangements required for large-scale credit creation and financial stability.
The more plausible transformation may involve competition and integration.
Stablecoin issuers could provide new payment infrastructure.
Banks may develop tokenized deposits and blockchain-based settlement services.
Financial technology companies may connect the two systems through consumer and business applications.
The result could be a financial landscape with more choices rather than one in which every conventional institution disappears.
The future of money may be a hybrid system
Stablecoins have introduced an important new possibility into global finance.
Money can be represented by transferable digital tokens and moved through networks that operate continuously.
This creates opportunities to improve selected payment processes and develop new financial applications.
However, the technology also raises questions about reserves, redemption, banking liquidity, consumer protection, and monetary sovereignty.
Traditional financial institutions retain advantages involving credit provision, regulation, and established customer relationships.
The next stage of financial development may therefore involve a combination of banking infrastructure and blockchain-based settlement.
Stablecoins are unlikely to replace traditional banking completely by 2030.
Their more realistic impact may be to force banks, payment companies, and financial regulators to redesign how money moves through the global economy, that what’s stated on Coinspot.Io.
If that happens, the future of money will not be defined by the disappearance of banks.
It will be defined by a financial system in which digital currencies and traditional institutions compete, cooperate, and gradually establish new standards for moving and managing value.